Beware of Option Selling
OTM option selling is sold as easy weekly income. Why the accuracy looks deceptively high, and how a single black swan day can erase months of small profits.
OTM option selling is promoted heavily these days as a common man’s tool for consistent returns of around 1% a week. Extrapolated, that is roughly 48% a year, which sounds very attractive. OTM option selling does have high accuracy, and small profits can be made consistently, so it is easy to feel confident about a selling strategy.
That confidence is false. One black swan day is enough to wipe out everything, or most of the profits.
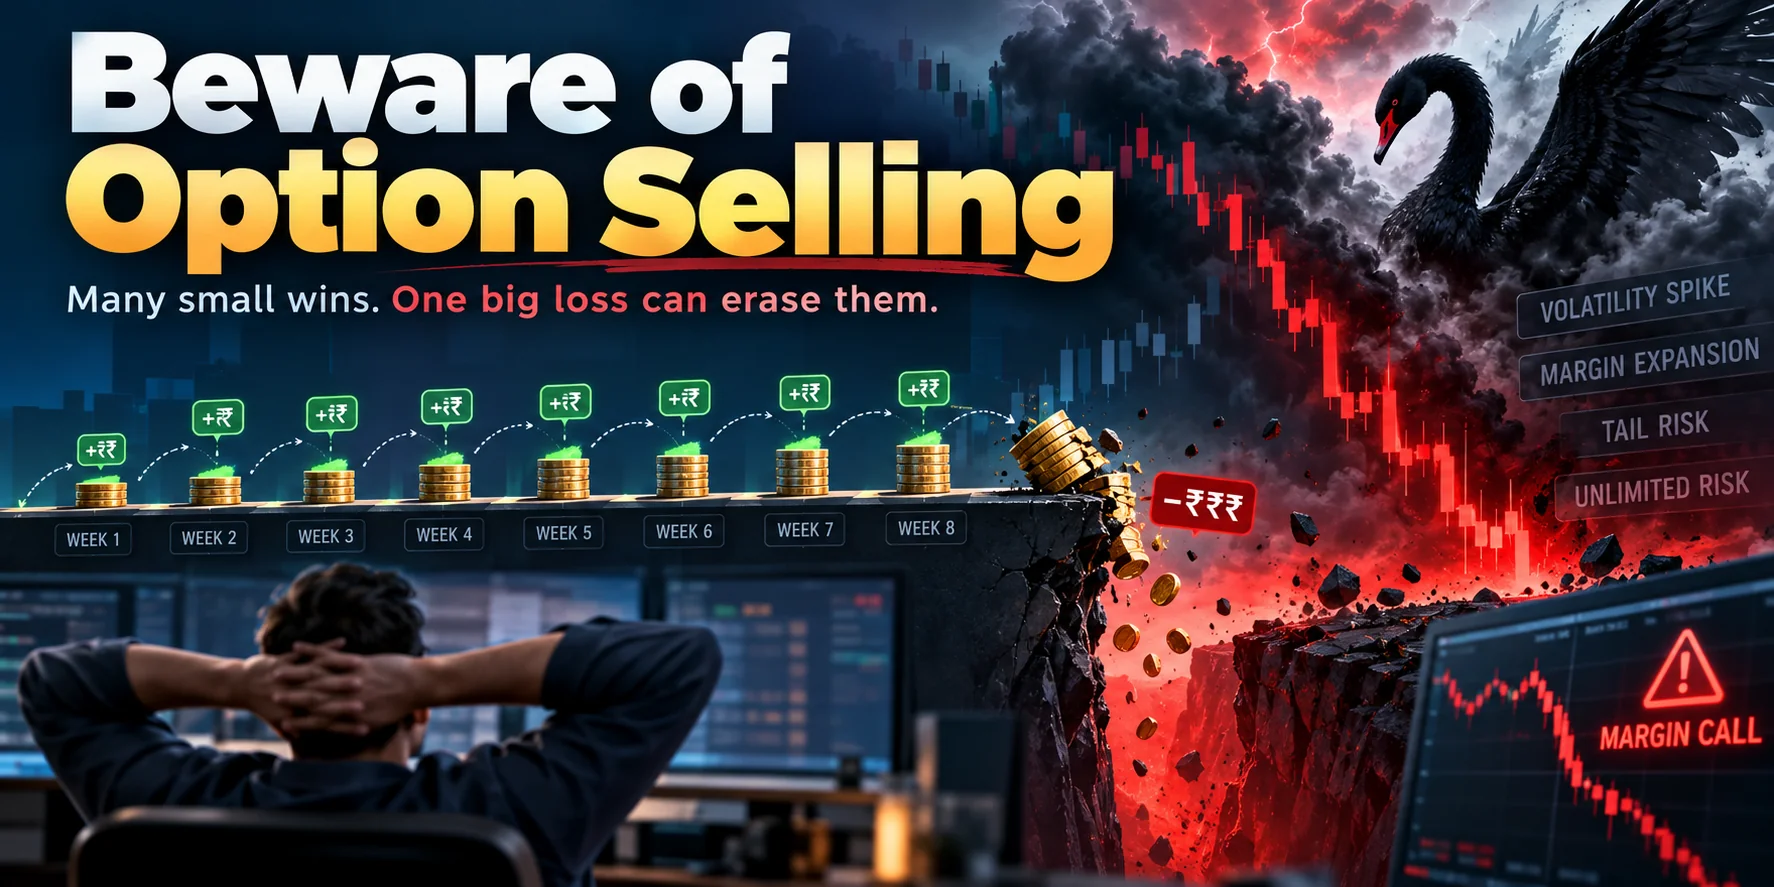
If you sell options, there are things you should know. Here they are, so you are not taken by surprise when lightning strikes, as it inevitably will one day or another.
What an option seller is exposed to
- A naked sell position has unlimited risk. If the market moves against the short position, you can lose any amount of capital in proportion to the move. You can hedge a naked sell with a long option, but even a hedge 150 points away caps the loss at around 15% of capital. That means the strategy needs to be more than 94% accurate just to break even, once the black swan day is accounted for.
- Margin is not constant. When you sell an option, the exchange blocks a margin amount that varies with the underlying price, its volatility, the time to expiry and more. Under fast-moving conditions the requirement can rise quickly and exceed your account funds. That leads to a margin shortfall and a penalty booked against your account, and your position may even be auto squared off by the broker’s risk team. This is true of both naked and hedged sell positions.
- It needs continuous supervision. As the market moves against you, adjustments and firefighting have to be done, and that takes real discretionary skill and time. It is not a passive activity by any stretch. Trading is a business that needs a certain capital kept aside, and the discretionary nature of option-selling firefighting means the exact capital required cannot really be estimated.
- Far OTM strikes are illiquid. A large position is needed to generate a fair profit, which makes entering and exiting illiquid options harder. You have to place limit orders and keep monitoring and adjusting them as the market moves, which is a significant time cost on every order.
- Options move wildly, especially at the open. Overnight stops are easily taken out during these swings, before the market settles. NSE has removed trade execution ranges for options, so think twice before deploying stops on OTM options.
- The margin benefit can be given away at some brokers. Under the prevailing rules you can get a margin benefit by buying an option first and then selling another. Some brokers, such as Zerodha, do not allow buying deep OTM options, so with them you give up that benefit and need more funds in the account.
- Brokerage scales with the number of legs. With a broker charging a flat ₹X per order, a one-legged naked option sell costs ₹2X per trade for entry and exit. A two-legged hedge such as a calendar spread costs ₹4X, and a four-leg Iron Condor costs ₹8X, before the brokerage on adjustments, firefighting and profit booking. There is a cost angle to a sell strategy, and small profits can easily be eaten by brokerage.
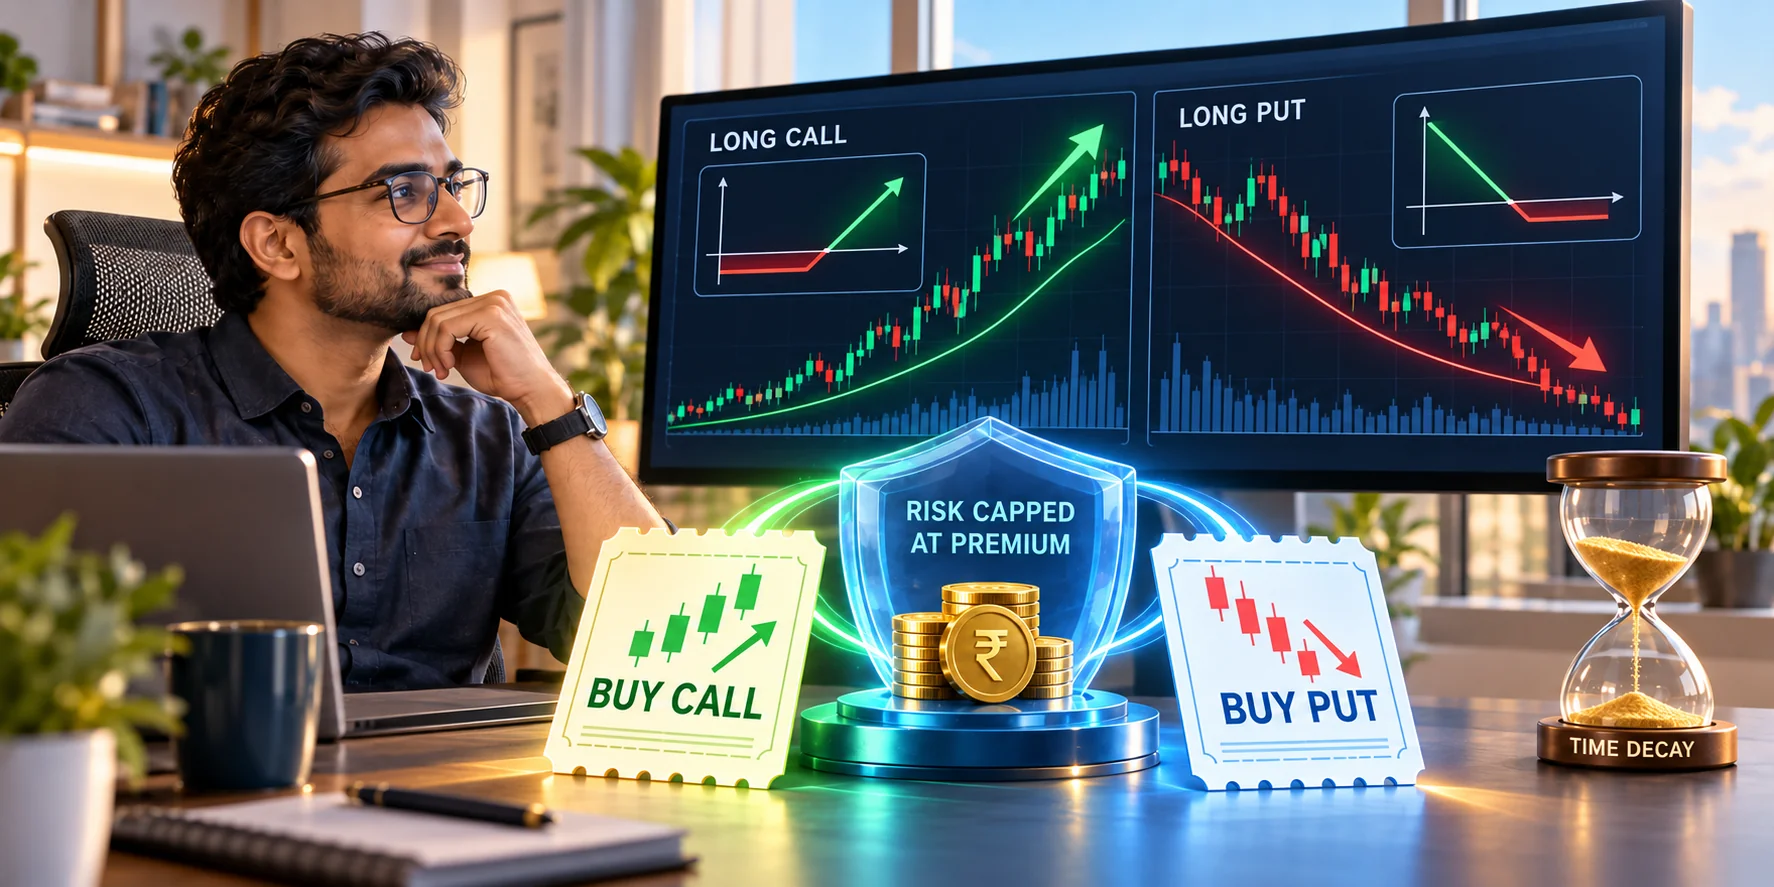
Courses can be sold, and strategy builders and OI-analysis platforms can be marketed, extolling the benefits of option selling and turning it into a business. Option buying can be campaigned against just as easily. But the fact remains that option selling is far riskier, and not as simple to understand or implement, as naked option buying.