Naked Option Buying Works
Naked option buying is usually dismissed out of hand. The case for it: capped risk, no margin, and how time decay and delta behave over a run of trades.
Most people frown upon naked option buying and advise against it. That is like saying:
- do not drive a car because you could have an accident, or
- do not play sport because you could get injured, or
- do not eat because pesticide-laden produce might give you cancer.
There are several instruments, tools and strategies out there, and it is up to us to use them according to our needs. Option buying can work, depending on the strategy’s metrics. Here are some obvious benefits.
Why option buying can work
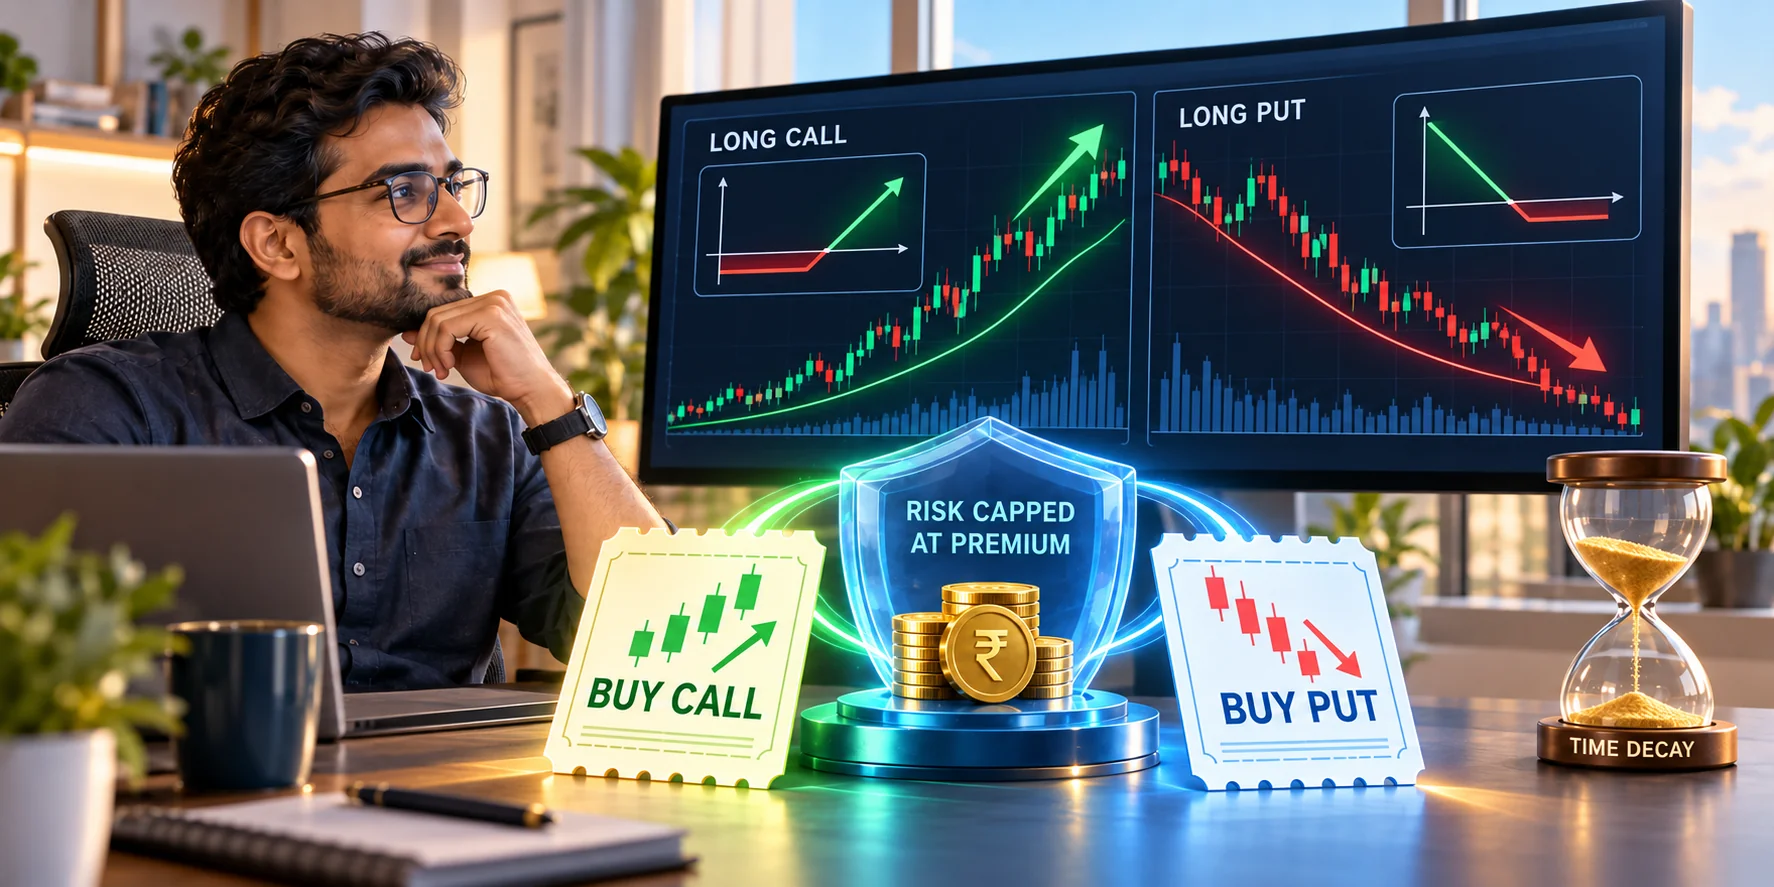
- Limited risk. A long option position cannot lose more than the premium paid for it, no matter what the market does.
- Unlimited profit. If the market moves in favour of the position, the trend can be ridden for as long as it lasts.
- Lower transaction cost. Much lower than futures, another instrument for riding trends.
- No leverage. A long option position uses only the money paid for the premium, with no pledging and no reliance on margin. There are none of the margin-shortfall penalties that option sellers have to stay alert to.
- Low capital. The premium paid for a bought option is far smaller than the margin a sell position blocks, so the capital exposed per trade is much lower than for selling, and even for hedged selling.
- Simplicity. It is easy to buy naked options in the direction of the trend, rather than committing yourself to complicated option-selling strategies, which also involve buying. When something is simple, it is also easy to follow, and following it is a critical part of profitable trading.
The time value question
Naked option buying does suffer from time value degradation. As expiry approaches, time value decays exponentially. That can be managed, and can even work in the buyer’s favour: if the winning trades are fewer than the losing ones, the time value effect balances out over a fair number of trades.
An option’s LTP does not move one-for-one with spot. For a weekly, near-the-money ITM option, delta is around 0.5 to 0.6 on a Thursday, a week before expiry, and it climbs towards 1 as expiry approaches. So a spot move of X points against the position does not cost the holder one-for-one, except on expiry day; the loss is in proportion to delta. A move in the holder’s favour does not pay one-for-one either, except on expiry day, for the same reason.
For a trend-following indicator such as TrendShikari NTS, accuracy is only around 47%. Over a fair number of trades the trends it catches pay for the time value lost on the ones that do not, so the time value effect is more or less negated by the accuracy. If a big trend runs for a few weeks, some part of it is given away to time value, but the capped risk of the naked option position counterbalances that when there are gaps against the overnight position. Markets have their minor gaps, and their major black swan days.